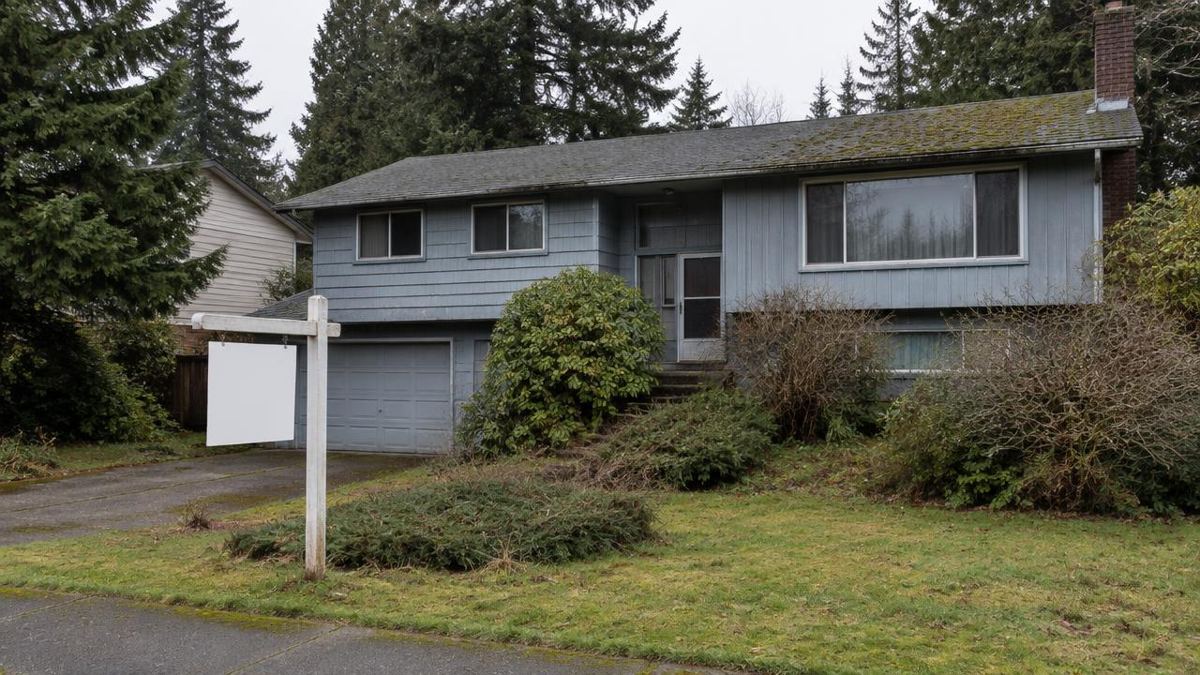
Short answer: An as-is clause does not itself remove Washington’s seller disclosure duties. Most improved residential sales require the statement specified by RCW 64.06.020, subject to applicable exemptions. Receipt, written notice, waivers and agreed terms matter to the generally applicable three-business-day rescission period. For a cash offer, verify actual funds and contract conditions and use a lawful, independently checked closing provider.
This guide covers Washington disclosure and cash-buyer checks. If you are still deciding whether repairs make sense, read the companion as-is versus repairs and net-proceeds comparison.
Washington's seller disclosure still applies
Washington's Seller Disclosure Act, RCW 64.06, requires sellers of residential real property to give the buyer a completed disclosure statement. For improved residential property, the required form language is in RCW 64.06.020 — Improved residential property disclosure; in NWMLS transactions this is Form 17. Writing "as is" in the listing or contract does not replace it.
Form 17 asks about title, water, sewer or septic, structure, systems and environmental issues. Under RCW 64.06.050, lack of actual knowledge limits liability for an error, inaccuracy or omission in the disclosure statement. That is not a universal standard for every seller obligation or a blanket exemption from other legal or contractual duties. Answer truthfully and do not guess; use “don’t know” only when accurate.
Exemptions
Some transfers are exempt under RCW 64.06.010, such as certain foreclosure, court-ordered and specific family transfers. Exemptions are narrow and fact-specific; ask a Washington real estate attorney before relying on one. Personal representatives of estates should confirm their obligations with the estate's attorney.
Lead-based paint
For homes built before 1978, federal law separately requires the lead-based paint disclosure and pamphlet, and gives buyers an opportunity to test for lead unless they waive it (EPA real estate disclosure rule).
The buyer's three-day rescission right
Under RCW 64.06.030, unless receipt has been expressly waived, the seller generally delivers the completed, signed and dated statement within five business days after mutual acceptance or as otherwise agreed. The buyer generally has three business days from receipt, or an agreed alternative period, to approve it or deliver written rescission notice. Early delivery can reduce late uncertainty but does not by itself extinguish statutory or contractual rights. Record actual receipt, review the signed terms and do not treat a verbal cancellation as the required written notice.
If the seller later learns that the statement is inaccurate, tell the broker immediately and review amendment and delivery requirements under RCW 64.06.040.
Step-by-step: an as-is sale in Washington
- Gather what you know. Repair records, permits, past inspection reports, septic or sewer information, and any insurance claims.
- Complete Form 17 carefully. Answer from actual knowledge; attach explanations where helpful.
- Decide whether to pre-inspect. A pre-listing inspection lets you price with known condition. Anything you learn becomes part of your knowledge for disclosure.
- Get a market valuation. Ask for an as-is price opinion based on comparable sales of homes in similar condition.
- Choose how to sell. List on the open market as-is, or request direct offers from cash buyers, or do both and compare.
- Review contracts and contingencies. Even an as-is buyer may include an inspection contingency; understand the deadlines.
- Use a lawful closing provider. Independently verify the provider and wiring instructions, review title and confirm lien payoffs and taxes. Escrow licensing exemptions exist, including the limited attorney exception in WAC 208-680-045 for escrow incidental to legal practice. A taxable sale may incur state and local REET; verify the sale date, property classification and exemptions with WA DOR.
How to find cash buyers for a neglected house
There are three common channels, and you can use more than one:
- Open-market listing marketed as-is. Exposes the home to investors, renovators and owner-occupants at the same time, which creates competition.
- Direct "we buy houses" investors and iBuyers. Fast and simple, but each buyer sets its own price; one offer gives you no comparison.
- Builders and renovators. For homes likely to be rebuilt, local builders may value the land and location more than the structure.
A neglected house can still attract strong investor interest in desirable locations. The best protection against underpricing is to get several written offers and compare them with a market valuation.
How to vet a cash buyer
- Request recent bank or brokerage evidence of available funds in the buyer’s or entity’s name, sufficient for the transaction. Independently confirm authenticity through a verified institution contact where authorized. A mortgage pre-approval or an earnest-money check is not evidence that the full cash purchase price is available. Protect account numbers and other private information.
- Look up business buyers on the Washington Secretary of State corporations search. Registration can help establish the entity’s identity; it does not verify available funds, reputation or the ability to close.
- Read the contract for assignment clauses; an assignable contract may mean the buyer plans to resell your contract to someone else.
- Check the earnest money amount and when it becomes non-refundable.
- Confirm inspection and feasibility deadlines and whether the buyer can renegotiate after inspection.
- Use an independently verified, lawful closing provider and review title-insurance coverage. Confirm whether the provider is regulated or is operating under a valid exemption. Do not transfer the deed or money solely on a buyer’s unverified instructions.
- Be cautious with any request for upfront fees or pressure to sign immediately.
Washington as-is sale: quick reference
| Item | Rule or practice | Source |
|---|---|---|
| Seller disclosure | Required for most residential sales, as-is or not | RCW 64.06.020 |
| Buyer rescission after receiving disclosure | Generally three business days unless agreed otherwise or waived | RCW 64.06.030 |
| Liability for disclosure-statement errors | RCW 64.06.050 limits liability for disclosure errors without actual knowledge; not all seller duties | RCW 64.06.050 |
| Lead paint disclosure | Homes built before 1978 | 42 U.S.C. 4852d; EPA |
| Excise tax | Seller pays graduated state REET plus local | WA DOR; RCW 82.45 |
| Foreign seller | Buyer generally withholds 15% under FIRPTA unless an exception or certificate applies | IRS |
Common mistakes in Washington as-is sales
Skipping or rushing the disclosure. Leaving answers blank or guessing creates risk. Answer from actual knowledge and say "don't know" when true.
Delivering Form 17 late. Giving the statement after mutual acceptance starts the buyer's rescission window late in the process. Provide it up front.
Accepting the first cash offer without a comparison. One offer tells you nothing about market value. Request several and compare them with a broker's price opinion.
Missing the assignment clause. Some buyers intend to assign the contract for a fee rather than close themselves. If you allow assignment, understand who will actually close and when.
Following unverified closing instructions. Independently confirm provider identity, payment instructions, title and payoff handling. A lawful escrow arrangement is a safety practice; not every lawful provider has the same license status, and no provider guarantees that every transaction risk disappears.
Frequently Asked Questions
Do I have to fill out Form 17 if I sell my house as is in Washington?
In most residential sales, yes. RCW 64.06.020 requires the disclosure statement regardless of an as-is clause, unless an exemption in RCW 64.06.010 applies.
Can a buyer cancel after receiving Form 17?
RCW 64.06.030 generally allows three business days after receipt, or an agreed alternative, to approve the statement or deliver written rescission notice. Review actual receipt, any express waiver and the signed terms; earlier delivery alone does not cancel rights.
How do I find a legitimate cash buyer?
Compare written offers, verify recent actual proof of available funds and the buyer’s identity, and review assignment, inspection and deposit terms. Business registration and mortgage pre-approval do not prove cash capacity. Use an independently checked lawful closing provider; valid licensing exemptions can apply.
Is a cash offer always faster?
Cash removes the lender timeline, but title, escrow and any inspection period still take time. Read the contract deadlines.
Sources and Further Reading
The official sources below explain the legal, tax, permitting and financing points discussed here. Rules apply to specific transactions and can change. Confirm the applicable requirements before acting. The numeric examples are illustrative unless a dated source is stated.
- RCW 64.06 – Real property transfers: seller’s disclosures
- RCW 64.06.020 — Improved residential property disclosure
- EPA – Lead-based paint real estate disclosure
- WA DOR – Real estate excise tax
- Washington Secretary of State – Corporations and Charities Filing System
- IRS – FIRPTA withholding
- WAC 208-680-045 — Limited attorney escrow licensing exception
- RCW 64.06.050 — Disclosure-statement error liability
- RCW 64.06.030 — Delivery, buyer options and written notice
- RCW 64.06.040 — Amended disclosure
Received a cash offer for a house that needs work?
Discuss your property and goals with the team. Contact Maggie Real Estate Group. Confirm the scope of any brokerage service before proceeding; lending, engineering and tax decisions belong with the relevant qualified professionals.
Related Guides
- Topic hub: Selling a house as-is in Washington
- Selling a house in probate in Washington
- Selling with Maggie Real Estate Group
- Should I Sell My House As Is? What It Means, What It Costs and When It Makes Sense
About the Author
Maggie Sun, Managing Broker, leads Maggie Real Estate Group, serving buyers and sellers in Seattle and the Eastside in English and Mandarin. This guide is general information, not legal, tax or lending advice; consult a Washington real estate attorney, CPA or licensed loan officer for your situation.
Last updated: November 2026.